Roof insurance in Highland Village
Separate the roof repair decision from the policy payment decision.
The roof condition and the policy answer different questions
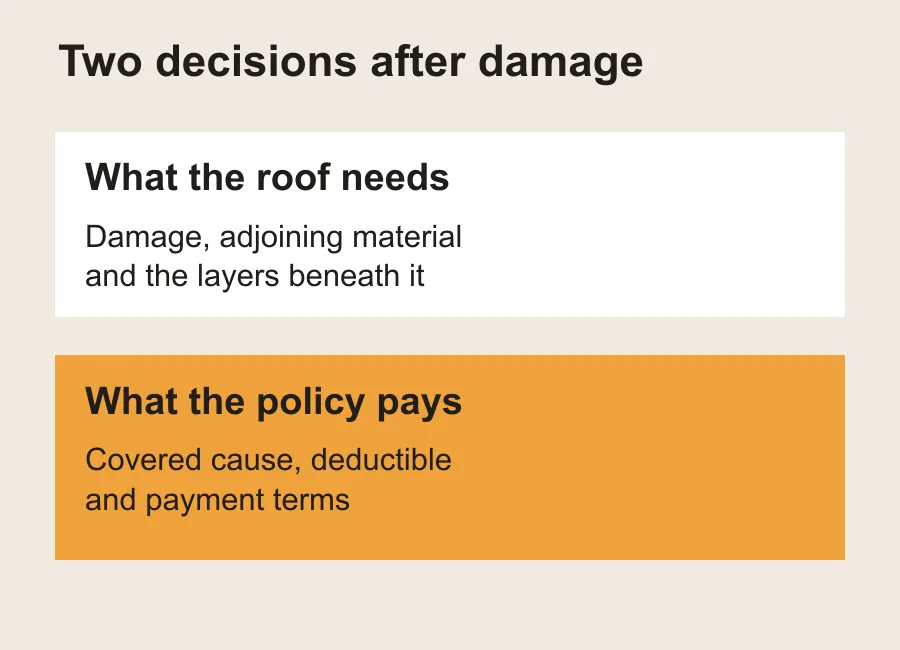
A damaged roof creates two questions: what work restores the roof, and what the policy pays toward that work. The inspection addresses the roof. The insurer applies the policy's coverage, deductible and payment terms.
The Texas Department of Insurance roof guidance, updated April 1, 2026 and checked September 30, 2026, explains the difference between replacement-cost and actual-cash-value coverage. Your own policy controls the claim.
A storm nearby, an old roof or an estimate for replacement does not by itself establish a covered loss. Keep the roofing scope and claim decision connected to their respective evidence.
How policy terms change a roof payment
These terms affect what may be paid even when the roof work is similar.
Roof work after a covered event
The roof still needs an accurate scope even when a claim is involved.
- Identify the damage and the affected work
The covering, flashings and layers below should be examined. A visible mark does not automatically require full replacement, while concealed deterioration can make a small opening a larger repair.
- Communicate with the insurer
Notify the insurer promptly about a potential covered loss and follow its claim instructions. Keep information about when the concern appeared and any photos already taken safely. Don't climb a damaged roof to gather evidence.
- Understand the proposed payment
The insurer's explanation should be read with the deductible, valuation and policy conditions. The project price and the covered payment may differ, especially where upgrades or unrelated wear are involved.
- Plan the actual repair
Temporary protection and permanent roofing work have different purposes. The finished repair needs suitable materials and sound connections, regardless of how payment is divided.
Highland Village roof insurance FAQs
Will insurance replace a roof because it is old?
Age and wear alone do not establish a covered loss. The cause of the damage and the policy terms control coverage.
Does a hailstorm in the area prove my roof was damaged?
No. The roof's condition needs examination at the property. A nearby event is context, not proof of the damage or replacement scope.
Can a shingle upgrade qualify for a discount?
It may, depending on the insurer, product and policy terms. Confirm eligibility before choosing the product on the assumption that a discount will apply.
Does a repair estimate above my deductible guarantee payment?
No. The loss must also be covered, and valuation, limits and other terms still apply. The deductible is only one part of the claim.
Can I request a free roof inspection before deciding what to do?
Yes. An inspection can help explain the roof condition and the work worth considering. Your insurer handles the coverage decision.
Start with what the roof needs.
A free inspection can explain the roofing condition while you work through coverage questions with your insurer.